
What Is a Home Appraisal and How Does It Work?
8 min read
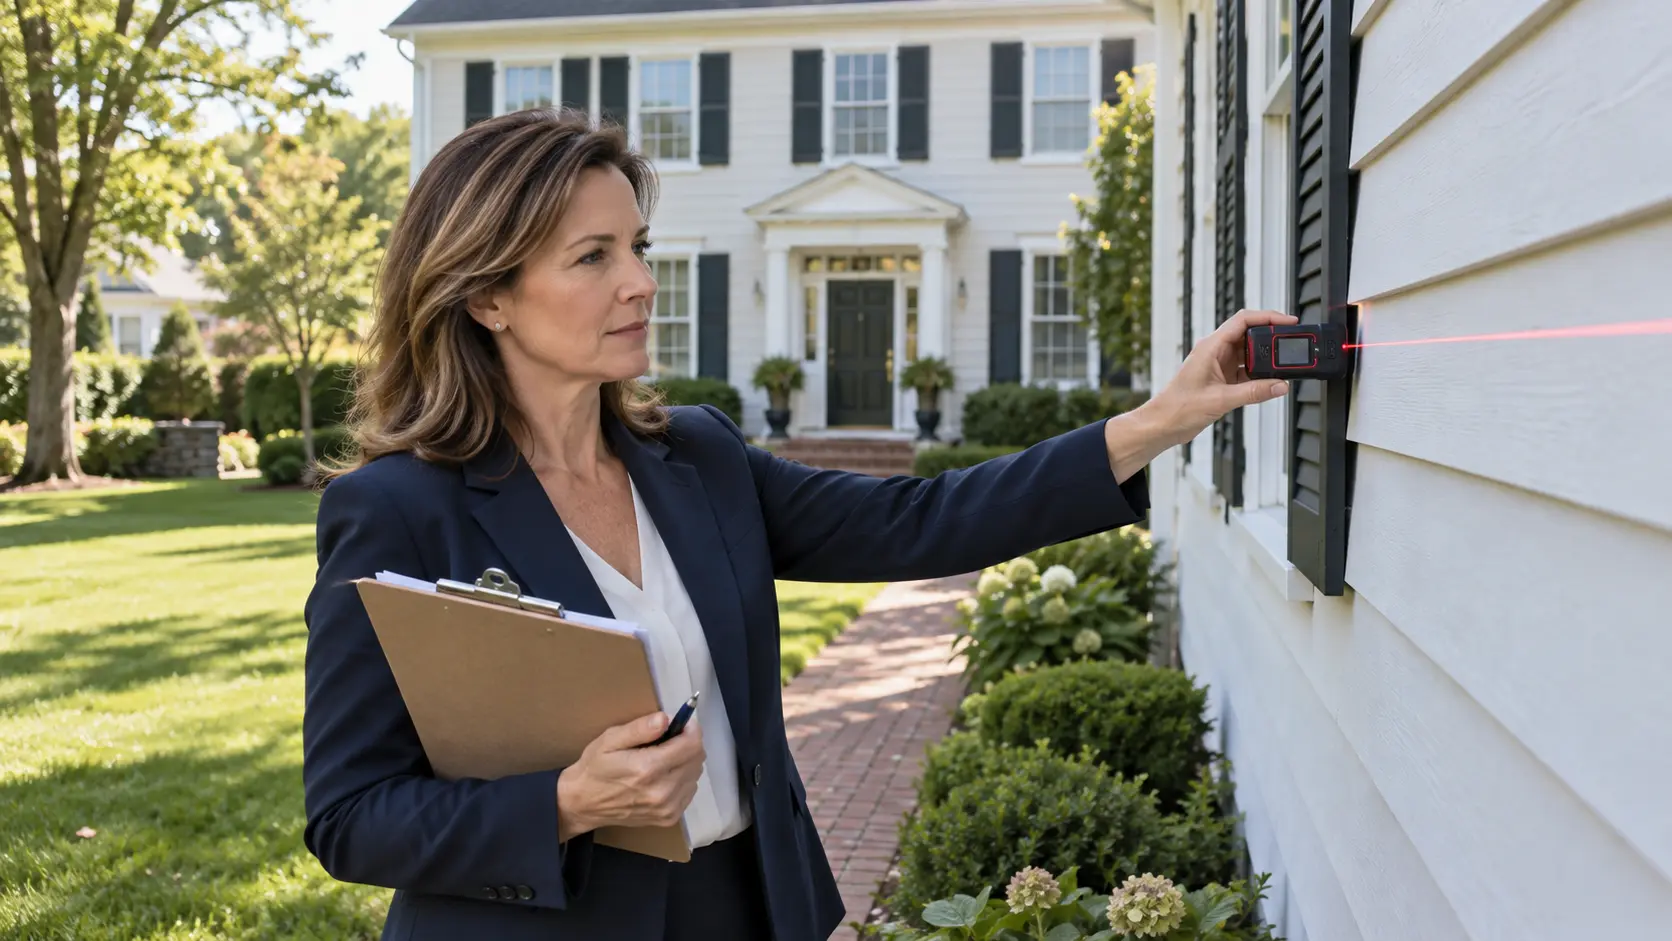
A home appraisal is a formal, licensed opinion of a home's market value, produced by a state-licensed appraiser through a physical inspection and analysis of comparable sales. It's not the same as the automated estimate you might refresh online at midnight: an appraisal carries legal and financial weight because a lender uses it to decide how much money it's willing to lend against the property. In this article, we walk through what a home appraisal is, how the process works, what it costs, how it differs from a home inspection, what happens when the appraised value comes in low, and why two similar homes can end up with different appraised values.
What is a home appraisal?
A home appraisal, sometimes called an appraisal on a home or on a house, is a professional, unbiased estimate of a property's market value, performed by a state-licensed appraiser who has no financial stake in the outcome. That independence is the entire point. An appraiser isn't working for the seller, the buyer, or even really the borrower who's paying for the report. They're working for the lender, producing a value opinion that the bank can trust when deciding how much money to hand over.
That distinction matters because people often conflate three very different numbers:
- Sale price: what a buyer and seller agree to on paper, which can be influenced by bidding wars, motivated sellers, or emotional attachment.
- Online estimate: an automated calculation based on public records and algorithmic modeling, useful for a ballpark but not built from an actual walkthrough of the property. A data-driven valuation like the free report from Kelley Blue Book Homes can offer a closer read here, since it factors in specific renovations and micro-market trends rather than relying solely on broad metro averages.
- Appraised value: a formal, defensible number based on in-person inspection and verified comparable sales, produced by someone accountable to licensing standards.
Lenders require an appraisal before approving a mortgage or refinance because they're not just betting on the borrower's ability to repay a loan. They're securing that loan against the physical asset. If a buyer defaults, the home itself is the collateral, so the bank needs assurance that the property is actually worth what it's lending against. Consult your loan officer or a licensed real estate attorney if you have questions about how an appraisal factors into your specific financing terms.
How does the home appraisal process work?
The home appraisal process moves through four main steps: the lender orders the appraisal, an appraiser inspects the property, pulls comparable sales data, and issues a formal report with a final value opinion. The specific details can shift depending on the property type and local market, but the sequence itself is fairly predictable.
1. The lender orders the appraisal
This typically happens after a purchase agreement is signed or after a refinance application is submitted. Importantly, the borrower doesn't get to choose the appraiser. Lenders work through appraisal management systems specifically to keep the process arms-length and free of pressure to hit a target number.
2. The appraiser inspects the property
This is a physical walkthrough, not a drive-by glance. The appraiser evaluates:
- Location: proximity to schools, employment centers, amenities, and overall neighborhood desirability.
- Physical characteristics: square footage, layout, age, structural condition, and any obvious deferred maintenance.
- Improvements: renovations, additions, or upgrades that may have added value since the last sale.
3. The appraiser pulls comparable sales
Known in the industry as "comps," these are recently sold homes in the same area with similar size, age, and condition. The appraiser adjusts for differences (an extra bathroom here, a bigger lot there) to arrive at a value estimate grounded in actual market behavior rather than guesswork.
4. A formal report is issued
This document lays out the appraiser's findings, methodology, and final value opinion. The lender uses it to confirm that the loan amount aligns with what the property is genuinely worth, protecting both the bank's exposure and, in a quieter way, the borrower from overpaying.
Worth noting: appraisal activity isn't static. Federal Housing Finance Agency data shows the volume of U.S. home appraisals rose 2.3% in the first quarter of 2024 compared to the same period a year earlier, and median appraised values for both purchase and refinance appraisals climbed from late 2022 into late 2023. Appraisals are a live reflection of a moving market, not a fixed formula.
How much does a home appraisal cost?
A home appraisal typically costs between $300 and $1,000, and while the lender orders it, the borrower almost always pays for it. The final price within that range depends on a few practical factors:
- Property size: larger homes take longer to inspect and analyze.
- Location: appraisers in dense urban markets may charge differently than those covering sprawling rural territory.
- Complexity: unique properties, unusual layouts, or homes with extensive renovations require more work to value accurately.
The lender-orders-it-but-borrower-pays-it setup surprises a lot of people, since it seems logical that whoever requests a service would cover its cost. The logic makes sense once you separate the two roles, though. The lender needs the appraisal to protect its own financial interest, but the cost of producing that protection gets passed to the person taking out the loan, similar to how borrowers often cover other closing costs like credit reports or title searches. It's a cost of doing business in a transaction where someone else's money is on the line.
How is a home appraisal different from a home inspection?
A home appraisal determines a property's market value for the lender, while a home inspection assesses a property's physical condition for the buyer. Confusing the two is one of the most persistent mix-ups in real estate, and it's worth untangling because assuming an appraisal covers safety and condition can leave buyers with a false sense of security.
What a home appraisal covers
A home appraisal answers whether the property is worth what the loan amount says it's worth. It's about the number, not the plumbing.
What a home inspection covers
A home inspection answers whether the house is structurally sound and what's likely to break or need repair. It's a completely different lens on the same property.
| Home Appraisal | Home Inspection | |
|---|---|---|
| Who it's for | The lender | The buyer |
| What it measures | Market value | Physical condition and defects |
| Who orders it | Lender (paid by borrower) | Buyer, voluntarily |
| Required by lender? | Yes, for most mortgage transactions (per lender/investor guidelines) | No, but strongly recommended |
| Outcome | A dollar-value estimate | A detailed condition report with findings |
An appraiser might note that a roof looks original to the home's construction, but they're not climbing into the attic checking for leaks or testing the heating, ventilation, and air conditioning (HVAC) system. That's the inspector's job.
A home can appraise at full value and still have a failing water heater or a cracked foundation. The appraisal simply isn't designed to catch that. Buyers who skip the inspection because "the appraisal already checked the house" are operating on a costly misunderstanding.
What happens when a home appraisal comes in lower than the offer price?
When a home appraisal comes in lower than the offer price, the loan amount gets capped near the appraised value, and the buyer and seller have to close that gap somehow before the sale can proceed. Picture a buyer who agrees to pay $350,000 for a home, but the appraisal comes back at $340,000. That $10,000 gap between what the buyer promised to pay and what the lender is willing to finance has to get resolved.
The typical paths forward:
- Renegotiate the price. The buyer goes back to the seller and asks them to meet the appraised value, splitting the difference or accepting the lower number outright.
- Buyer covers the gap in cash. Since the loan amount is now capped near the appraised value, the buyer can choose to bring the difference to closing out of pocket to keep the deal at the original price.
- Challenge the appraisal. Buyers or agents can request a reconsideration of value if they believe the appraiser missed relevant comps or made an error, though successful challenges are the exception, not the rule.
- Walk away. If the purchase agreement includes an appraisal contingency, the buyer can back out without losing their earnest money.
Because these options can affect contract deadlines and earnest money, buyers navigating a low appraisal may want to consult their real estate agent or a real estate attorney before deciding how to proceed.
Appraisal gaps aren't rare edge cases: they tend to spike whenever the market moves faster than sales data can keep up. During the pandemic-era buying frenzy, bidding wars regularly pushed offer prices well above what recent comps could justify, since appraisers are anchored to closed sales, not the emotional momentum of a hot week. When prices climb fast, appraised values often lag a step behind, and that lag is exactly where these gaps are born.
Why do appraised values differ for similar homes?
Two houses that are nearly identical in square footage, age, and condition can still land on different appraised values because of factors ranging from school district boundaries to documented bias in the appraisal industry. Some of that gap comes down to legitimate market factors, like subtle differences in comps, but research has surfaced a more troubling pattern that goes beyond ordinary market variation.
A 2018 Brookings Institution study found that homes in majority Black neighborhoods are appraised at roughly 23% lower than comparable homes in neighborhoods with few or no Black residents, even after controlling for similar home quality. That's not a rounding error. It's a systemic gap that shows up across markets, and it's drawn attention at the federal level. In 2023, a White House task force was formed specifically to address appraisal bias, with then-Vice President Kamala Harris stating plainly, "Home appraisals are meant to be fair and objective estimates of the market value of a property. However, far too often they are not."
The takeaway for buyers, sellers, and homeowners isn't that every appraisal is suspect. It's that the process, while designed to be objective, hasn't always delivered on that promise evenly across every neighborhood, which is why understanding your rights around requesting a reconsideration of value is worth knowing.
What does a home appraisal mean for sellers?
For a seller, the home appraisal is ordered by the buyer's lender after the offer is accepted, so the seller does not choose the appraiser or set the timing. What the seller can do is have receipts for recent improvements ready for the walkthrough, since documented upgrades are the easiest thing for an appraiser to credit.
An independent estimate before listing is not an appraisal and does not replace one. The buyer's lender will still order its own, and that report is the number the loan is built on.
How Kelley Blue Book Homes can help
Knowing how an appraiser arrives at a number is useful, but it doesn't tell you what your home is worth right now, before a lender, a buyer, or a contingency clause enters the picture. Getting an independent read on that number ahead of time can make every later step, from listing to negotiating a low appraisal, less of a guessing game.
Kelley Blue Book Homes brings the independent pricing authority Kelley Blue Book built over nearly a century to residential real estate. Its free home valuation report is engineered to land within 3% of the final sale price, built on neighborhood-level data that accounts for your specific renovations, micro-market trends, and seasonal timing rather than broad metro averages.
You can get a customized and independent home estimate quickly, and turn that initial estimate into a strategy with the support of a verified local expert from Kelley Blue Book Homes. Get your free home value report at KelleyBlueBookHomes.com.
Keep reading
How Real Estate Agents Value Your Home
Are you preparing to sell your home? Accurate home pricing is crucial for getting a buyer.
What Is a BPO (Broker Price Opinion)?
A Broker Price Opinion (BPO) is a professional estimate of a property's value. A BPO is prepared by a licensed real estate agent or broker who uses their…
What Home Inspectors Look For (and What It Means for Your Price)
What home inspectors look for, from foundation to HVAC, plus common problems, typical repair costs, and whether new homes need inspections too.
Unlocking Your Home's True Value: Lessons From the Car Market
When you're thinking about selling your home, one of the biggest questions you'll face is: "What's my house really worth?" It's the same question millions…